$STRC Catalyst Posts
July 12, 2026Single-day social intelligence recap and verified catalyst posts · ← Back to $STRC Profile · Market Rankings
💬 Curated Viral Posts & Community Evidence
16 source posts analyzed· 2026-07-12T12:52:19+00:00Looking forward to seeing the announcement tomorrow. As a $MSTR shareholder I am happy to be patient and wait for the following to occur: 1) Elimination of the $6.7B in convertible debt. 2) Increased adoption of $STRC and S&P 500 inclusion. Staying the course.
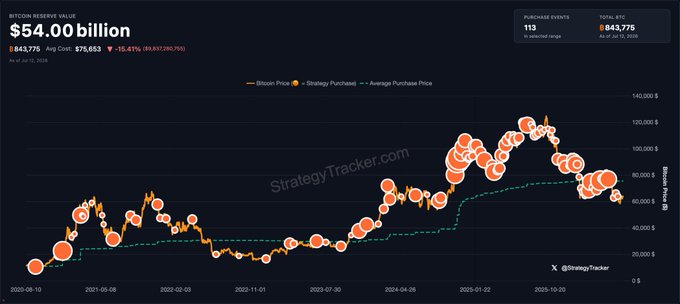
AI visual analysis: The image is a chart from StrategyTracker.com showing MicroStrategy's (MSTR) Bitcoin holdings, valued at $54.00 billion with an average purchase price of $75,653 and a -15.41% return, tracking the company's BTC purchases since 2020-06-10. This relates to the post about being a patient MSTR shareholder awaiting the elimination of $6.7B in convertible debt and increased STRC adoption, as the chart visualizes the scale of MicroStrategy's Bitcoin treasury strategy that the shareholder is committed to.
· 2026-07-12T18:59:28+00:00$STRC is objectively a better deal at $85 than at $100. I’m buying precisely 17% more $STRC every couple weeks at 85 than I was at 100, and receiving a higher effective yield. Long term better for the company to let people like me soak up the supply at a discount. The reason
· 2026-07-12T14:35:44+00:00Finally took a break this weekend, throwing everything aside (actually paid to go through some grueling training to lose weight ) Looking back at the past 6 days, intense long-short battle at the 64k level MSTR and STRC have stopped falling But next week is packed with
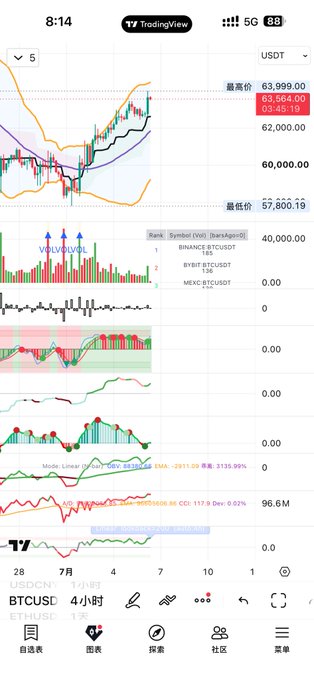
AI visual analysis: A TradingView chart of BTCUSD on the 4-hour timeframe shows Bitcoin trading at approximately $63,564 with a recent peak of $63,999 and low of $57,800, illustrating the intense long-short battle around the $64k level mentioned in the post. The chart includes volume bars, Bollinger Bands, and several technical indicators with multiple bullish (green) and bearish (red) signals visible across the lower panels.
· 2026-07-12T17:10:36+00:00Now available to trade on Bullpen: $STRC (Strategy)
AI visual analysis: A dark promotional graphic for Bullpen features "10x Leverage" in a green badge at the top left, "New Perp" in green above the large white text "Strategy ₿", with "app.bullpen.fi" displayed at the bottom left and a green Bullpen logo at the bottom right. The image directly mirrors the post's announcement by highlighting Strategy's new perpetual futures contract ($STRC) now available for trading on the platform with up to 10x leverage.
· 2026-07-12T14:25:00+00:00Getting $STRC back to par is the top priority. In my view, the most likely path is increasing the USD reserve through the common ATM. 2–3 years of dividend coverage should be enough.
AI visual analysis: The image is a Strategy Tracker chart showing MicroStrategy's (now "Strategy") Bitcoin reserve value of $54.00 billion, with a running total of 112 purchase events accumulating 583,275 BTC at an average price of ~$75,653, plotted against Bitcoin's price from mid-2023 to mid-2025. The chart illustrates the company's aggressive and sustained BTC accumulation strategy, providing context for the post's discussion about funding mechanisms—specifically how using common ATM offerings to build USD reserves could support dividends and maintain $STRC's par value, rather than relying solely on Bitcoin-backed capital raises.
· 2026-07-12T14:49:29+00:00He probably sold Bitcoin 1) They could be to improve the cash reserve. 2) Re-buy MSTR or STRC. 3) Pay off convertible debt. What do you think?
AI visual analysis: A StrategyTracker.com chart shows MicroStrategy's Bitcoin reserve value at $54.00 billion, with 842,775 BTC purchased at an average price of $75,653, currently valued at $64.3 billion—aligning with speculation that the company may have sold Bitcoin to improve cash reserves, repurchase MSTR/STRC shares, or pay off convertible debt.
· 2026-07-12T16:41:36+00:00Qué pasaría con $STRC y @MicroStrategy si #bitcoin cayera a $20.000 @saylor responde [Spoken audio]: ¿Qué le pasaría a Stretch si Bitcoin cae a 20,000 o 50,000? ¿Entraríamos en un mercado bajista aún más frío y permaneceríamos allí durante 18, tal vez 24 meses? ¿Los inversionistas seguirían recibiendo el rendimiento prometido? ¿Y hay un punto en el que perderían su capital? La empresa está muy sobrecolateralizada actualmente en este momento. que el riesgo en la empresa es, yo lo dividiría así, creo que tenemos alrededor de 4.000 millones de dólares en deuda neta y 52.000 millones de dólares en activos en este momento, o quizá 50.000 millones. Así que si Bitcoin cayera un 90, 92%, eso sería muy malo para el capital. Tendríamos que refinanciar la deuda, ¿verdad? Y probablemente eso haría que el crédito se negociara débilmente al 90%. Pero no creo que incompliéramos con nada. Si Bitcoin cae un 100%, entonces tenemos un problema. Líos peores que el resto. ¿Verdad? Si cae un 100%. Si cae un 90%, eh, entonces probablemente el crédito se negocie débilmente y la deuda se refinancia. Si Bitcoin cae un 70%, eh, creo que todo el crédito y toda la deuda se resuelven bien y de nuevo no puedo garantizar a qué precio se negocia todo el crédito porque eso depende del sentimiento del mercado, pero no dejaríamos de pagar los dividendos. Si la mayor parte del riesgo está estructurada para estar en el capital, en el capital de MCTR. El capital está amplificado tanto a la alza como a la baja, así que si eres adverso al riesgo, entonces ya sabes realmente no eres un inversionista en acciones. Si, si fueras el inversionista de crédito más adverso al riesgo, simplemente comprarías los bonos que tenemos. Los bonos de hecho están sobrecolateralizados en promedio 12 a 1 y algunos de ellos están colateralizados como 81, ¿verdad? Y así que creo que calculamos el rendimiento imputado de BTC de los bonos. El rendimiento imputado de BTC de los bonos actualmente está valorado en menos 60% al año. ¿De acuerdo? Loco. O sea, los bonos son ellos. Las personas que tienen los bonos literalmente piensan que Bitcoin va a llegar a cero en diez años o en cinco años. Y no les importa, ¿verdad? Y aún así los bonos se pagan. El rendimiento imputado en BTC del crédito es como menos ocho por ciento, así que los diferenciales de crédito sobre el crédito asumen que Bitcoin cae un ocho por ciento para siempre o un nueve por ciento para siempre. Entonces si realmente crees que Bitcoin va a superar el menos nueve por ciento, entonces el crédito está en muy buena forma. Creo que el tramo de crédito senior es STRF. Está sobrecolateralizado nueve veces, nueve a uno, y luego ese 13 es 3.1 a uno. Por supuesto, si tienes Bitcoin estás colateralizado uno a uno, ¿verdad? Así que el punto es Bitcoin, sí, tal vez algo muy simple para observar ahora mismo es, es el retorno total de STRC en los últimos como 10 meses desde el máximo histórico de Bitcoin, es como menos 5% o menos 3% algo así. Y el retorno total de Bitcoin es menos 50%. Así que, efectivamente, hemos eliminado el 90% del riesgo de Bitcoin en medio de un mercado bajista con STRC. Así que, creo que esa es una respuesta corta. Si crees que Bitcoin va a caer más del 80%, probablemente no quieras mantener la acción y tal vez tampoco quieras mantener el crédito si piensas que Bitcoin va a ser volátil y se va a mover de manera lateral. Creo que la forma en que funciona es si si crees que Bitcoin va a ser comparable al índice S&P entonces todo este crédito es de grado de inversión. Por ejemplo si quieres hacer una simulación puedes ir a nuestro sitio web ir a la pestaña de crédito y en realidad se actualiza cada 15 segundos y puedes ingresar tu perspectiva futura sobre la volatilidad de bitcoin y tu perspectiva futura sobre el precio de bitcoin y puedes ingresar números negativos. Bitcoin caerá un 9.8% anual para siempre y puedes ingresar la volatilidad lo que verás y te muestra el riesgo y el diferencial de crédito justo y lo que descubres cuando haces eso es que el riesgo es muy sensible a la volatilidad. La diferencia entre una volatilidad de 45 y una de 40 en Bitcoin son 200 puntos básicos de diferencial de crédito. Y la diferencia entre si Bitcoin cae a una volatilidad de 30, todo esto empieza a aparecer de grado de inversión. Si Bitcoin sube un 10% anual, todo es grado de inversión. Así que para un maximalista que cree que Bitcoin subirá un 30% al año, no hay riesgo. Si eres escéptico y piensas que Bitcoin va a caer un 10% al año, está justamente valorado a los diferenciales de crédito actuales. Así que lo realmente interesante para un inversionista de crédito es que hemos creado un crédito homogéneo y transparente y puedes calcularlo con un modelo de distribución estadística log normal cada 15 segundos y Y puedes, si ni siquiera sabes de qué estoy hablando, puedes ir a cualquier IA y pedirle a la IA que genere el modelo de crédito por ti y lo hará. Así que realmente no puedes evaluar el crédito privado, no puedes evaluar el crédito hipotecario, no puedes evaluar el riesgo de crédito corporativo, ni el riesgo de crédito soberano de esta manera. Pero con el crédito digital puedes evaluarlo y luego puedes cubrirlo y puedes negociarlo. Y, por supuesto, creemos que es el mejor tipo de crédito del mundo porque estamos extrayendo este instrumento de crédito puro de un bloque de capital digital. Yes, es increíblemente escalable, increíblemente transparente. Y como muchas cosas, para mí era bastante obvio que Apple y Amazon no iban a desaparecer en 2010. De hecho, literalmente escribí un libro sobre eso. Y hoy en día parece bastante obvio para el resto del mundo. Pero en ese momento era totalmente una operación fuera del consenso. Podría saber multiplicado tu dinero por 20, ya sabes, en ese momento. Y me parece bastante obvio que Bitcoin no va a desaparecer. Si crees que Bitcoin no va a desaparecer, entonces, de hecho, mi punto para ti es que si realmente piensas que Bitcoin no va a desaparecer, la jugada ganadora es el crédito, Porque el crédito está valorado por personas que piensan que Bitcoin va a desaparecer en la próxima década, ahora mismo. Y eso creo que es lo interesante que está ocurriendo en el mercado.

· 2026-07-12T14:21:52+00:00I feel like Saylor probably won't buy coins. Before STRC gets back to 100, they'll likely keep making moves around $STRC. Increasing cash reserves, buybacks, and eliminating debt are all possibilities.
AI visual analysis: The image is a StrategyTracker.com chart showing MicroStrategy's (now Strategy) Bitcoin holdings valued at $54.0 billion, with 843,775 coins acquired at an average price of $75,653 (-15.41% from current $64,375 BTC price), alongside 112 purchase events totaling $33.25 billion. The chart relates to the post by illustrating MicroStrategy's massive BTC reserves and suggesting Saylor may focus on STRC stock moves and capital strategies rather than additional Bitcoin purchases.
· 2026-07-12T06:04:36+00:00Someone's actually asking which one to buy, $STRC or $SATA, as the core asset for all Bitcoin credit (Digital Credit)? Let me give the answer upfront: it has to be $STRC. The issuer of STRC is @Strategy , and the issuer of SATA is @Strive . Strategy holds over 840,000 BTC in

AI visual analysis: A close-up selfie of a man with glasses taken inside a car, with Chinese text "投资别学我" (which translates to "Don't learn investing from me") displayed at the top of the image.
· 2026-07-12T12:40:51+00:00havent seen the strc chart in a bit
AI visual analysis: A simple black ink drawing of a man in a white collared shirt and black tie with a neutral expression, sketched on white paper. The hand-drawn portrait appears to represent a person (possibly a financial figure or commentator) being humorously associated with the "strc chart" mentioned in the post.
· 2026-07-12T14:28:46+00:00Spam is hard to define. That’s precisely why BIP-110 isn’t called “Ban Spam.” It’s called the “Reduced Data Temporary Softfork.” Anyway, let’s play your game. Things worse for Bitcoin than spam: 1. Michael Saylor 2. Strategy 3. MSTR 4. STRK 5. STRF 6. STRD 7. STRC 8. STRE 9.
· 2026-07-12T07:01:11+00:00Why does sUSDat fall less than apyUSD when STRC price drops? Core answer: The asset portfolio structures are completely different. sUSDat has stable buffers + dynamic risk controls, making it more resilient; apyUSD is heavily weighted toward volatile preferred shares, facing
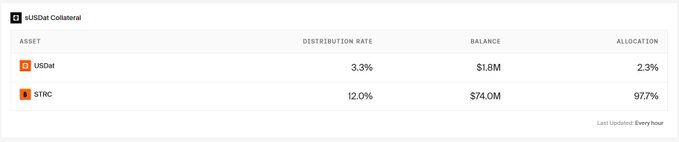
AI visual analysis: A dashboard for sUSDat Collateral showing asset distribution: USDat at 3.3% rate with $1.8M balance (2.3% allocation) and STRC at 12.0% rate with $74.0M balance (97.7% allocation).
· 2026-07-12T12:41:22+00:00THE BEST WAY TO PLAY A NARRATIVE ISN'T ALWAYS THE NARRATIVE ITSELF Sometimes... It's the business behind it. Robinhood hype is a perfect example. $ARB benefits as protocol fees flow into the treasury. $UNI captures massive trading volume. During the $STRC yield narrative...
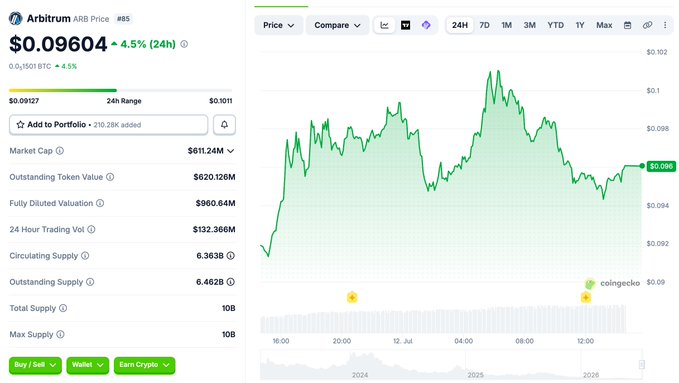
AI visual analysis: A CoinGecko price page for Arbitrum (ARB) showing a current price of $0.09604, up 4.5% in 24 hours, with a market cap of $611.24M and 24h trading volume of $132.366M. A green line chart displays the price movement over the selected timeframe.
· 2026-07-12T14:45:37+00:00¿Renta fija respaldada por #Bitcoin? Así paga cada preferente Fichas con precio y yield en vivo → satsintel.io/preferentes ▸ $SATA @Strive - 13% · pago CADA DÍA HÁBIL ▸ $STRC @Strategy - 12% · 2 pagos al mes ▸ $STRF - 10% · trimestral ▸ $STRD - 10% · trimestral ▸
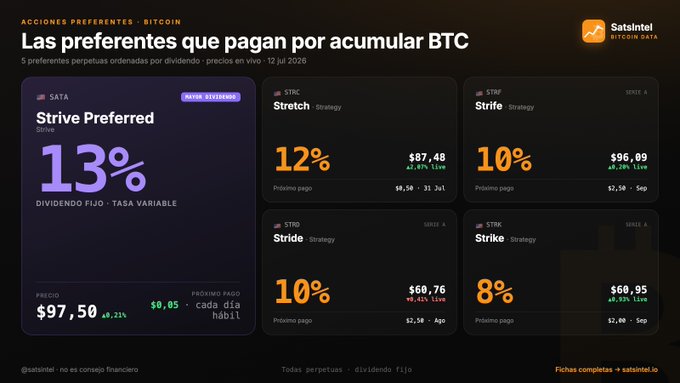
AI visual analysis: A SatsIntel Bitcoin Data infographic in Spanish titled 'Las preferentes que pagan por acumular BTC,' showing five preferred stocks ordered by dividend yield, led by SATA Strive Preferred at 13% (price $97.50), followed by STRC, STRF, STRD, and STRK.
· 2026-07-12T11:01:24+00:00比特币信用的核心资产相比SATA, STRC 明显目前有更强的机会 STRC是由 Strategy Inc.(前 MicroStrategy,MSTR,由 Michael Saylor 领导)发行 SATA是由 Strive Inc.(ASST)发行 这两个都是比特币支持的永久优先股,通过可变股息率将价格锚定在约 100
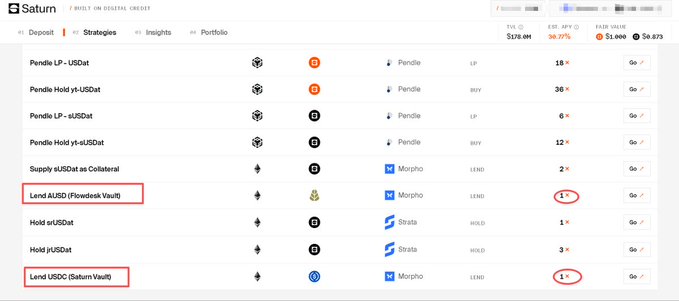
AI visual analysis: A screenshot of the Saturn DeFi Credit protocol interface showing various Pendle and Morpho strategies, with red boxes highlighting 'Lend aUSDT (Flowdesk Vault)' and 'Lend USDC (Saturn Vault)'.
· 2026-07-12T12:38:11+00:00Strategy selling BTC to pay interest is the financial equivalent of a firm selling off its own factory equipment to pay dividends to shareholders. $STRC is massively overpriced by $53.91/share, overpaying 38.4% against QQQ. The yield should be much higher for the risk.