$BASE
StableSnapshot Window: 2026-09-19 15:30 UTC · ← Back to Crypto Overview
Social Momentum Summary
Total Engagement - Comments: 0, Retweets: 0, Likes: 0, Impressions: 1
Verbatim Community Citations & Social Evidence 1 source posts analyzed
IF YOU'VE GOT DEBT AND SAVINGS AT THE SAME TIME, WHO ACTUALLY WINS FROM THE FED'S NEW RATE HIKE? Savers come out on top. High-yield savings, CDs, and money market funds move closely with short-term rates, and some accounts already pay near 4% APY, way above the 0.63% national
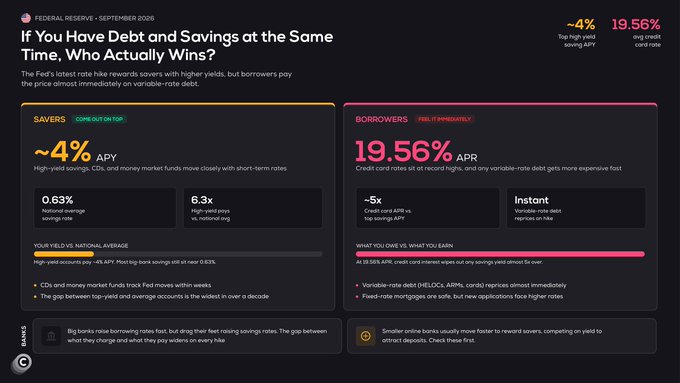
AI visual note: The image is a Federal Reserve infographic comparing the impact of the September 2026 rate hike on savers vs. borrowers, showing savers benefiting with ~4% APY on high-yield savings/CDs/money market funds (vs. 0.63% national average), while borrowers pay an immediate 19.56% APR on credit cards and other variable-rate debt. It visually reinforces the post's message that those holding both debt and savings simultaneously benefit more from rising rates as savers than they lose as borrowers.